
Verona, 11/10/2026
Consolidated Financial Results as at 30 September 2026
REVO: GROWTH CONTINUES IN ITALY AND SPAIN, ON TRACK TO ACHIEVE ITS FIRST-YEAR BUSINESS PLAN TARGETS
Gross written premiums amounted to €314.3 million (+12.0% compared with the third quarter of 2025), with an adjusted¹ operating result of €44.6 million and adjusted net profit of €25.7 million. REVO Iberia’s gross written premiums amounted to €14.1 million (+83.7% compared with 30 September 2025).
IFRS 17 Results:
Revenues from insurance contracts €253.7 million
Result of insurance services €36.8 million
Net financial result €7.0 million
Operating profit €41.1 million
Adjusted¹ operating profit €44.6 million
Net profit €21.3 million
Adjusted¹ net profit €25.7 million
Combined ratio IFRS 17² 85.3%
Group Solvency II ratio 214.8%
During the quarter, implementation of the “THE TECHUMAN ERA” Business Plan continued along its strategic pillars: technological innovation, product development, algorithmic underwriting and the strengthening of distribution channels.
In the technology area, progress was made on Artificial Intelligence projects, the Digital Twin development program and the further evolution of the proprietary OverX platform.
Concerning algorithmic underwriting, the tools supporting risk assessment and selection were further enhanced, including through the introduction of automated triage based on the Company’s risk appetite. This enables preferred risks to be pre-selected and improves the operational efficiency of the underwriting team.
As regards product development, REVO recorded growth across its main Specialty segments, particularly Surety, Energy, D&O and Legal Protection, together with further growth in its parametric solutions. The Bancassurance business also strengthened, through cooperation with UniCredit and Banco Desio.
The consolidation of distribution channels and the expansion of the Company’s international presence are ongoing, particularly in Spain, where both the team and commercial opportunities continue to grow.
As at 30 September 2026, the Company’s distribution network comprised 120 agencies, 69 brokers and 17 foreign brokers, while REVO Underwriting’s network totaled 437 intermediaries.
Verona, 11 November 2026 - The Board of Directors of REVO Insurance S.p.A., parent company of the REVO Insurance Group, today approved the consolidated results for the third quarter of 2026.
STRATEGIC DEVELOPMENTS DURING THE QUARTER
During the quarter, the following activities were carried out in line with the strategic objectives set out in the Business Plan:
Progress in Artificial Intelligence projects, with new solutions integrated into insurance underwriting and claims management processes, aimed at increasing productivity and streamlining operational activities, while retaining human oversight as a safeguard for control and reliability;
Continued development of the Digital Twin, as envisaged in the Business Plan and covering the Company’s main functions. The preparatory activities and initial findings confirm encouraging prospects in terms of potential applications and integration into the Company’s processes;
Further development and consolidation of the OverX platform, through the expansion of its after-sales functionalities, the broadening of its commercial offering through a new underwriting process supporting trade credit products, and the integration of new parametric solutions. The platform has also been enhanced with risk triage based on the Company’s risk appetite, providing an initial automated screening mechanism for the assessment of quotation requests received from intermediaries;
Extension of algorithmic underwriting to new products, with the first applications already scheduled for implementation during the year in the Cyber, Property and Legal Protection lines;
Positive performance in the Specialty segment, with Surety gross written premiums increasing by 11.4% compared with the first nine months of 2025 and exceeding Business Plan expectations. Energy also reported positive performance, with premiums amounting to €8.8 million, compared with €4.5 million in the corresponding period of 2025. A summary table showing the breakdown of premiums is provided below:
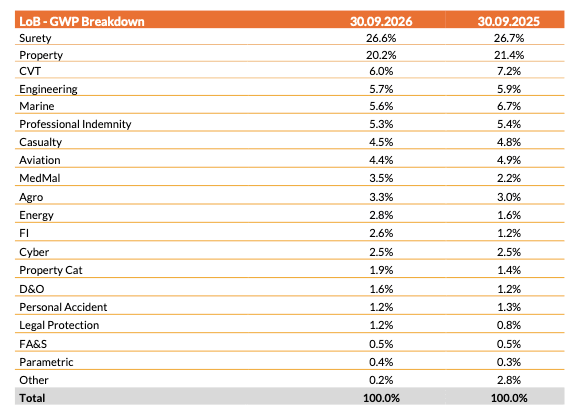
Strengthening of the Company’s specialization in Cyber, through a dedicated “Cyber, Digital & Technology Lines” unit focused on business development in Italy and Spain, by consolidating technical, commercial and underwriting expertise and increasing the focus on a segment characterized by constantly evolving market dynamics and risks;
Further growth in parametric solutions, one of the Company’s main innovation drivers: as at 30 September 2026, the number of policies sold had reached 118,000 (+47% compared with 2025). In the Travel segment, the new product for travel agencies, launched in July, recorded 3,700 policies. In September, a partnership with AMI Assistance was also launched to expand the offering dedicated to this sector;
Continued strengthening of REVO Underwriting’s distribution network, which comprised a total of 437 intermediaries as at 30 September 2026, an increase of 46 compared with 30 June 2026. This confirms the agency’s development path and the gradual expansion of its market presence, in line with the Business Plan objectives;
Consolidation of the Company’s international presence in Spain, accompanied by growth in the local team and the planned relocation, by year-end, to the new offices in Madrid, in the heart of the capital’s financial district. Business development and distribution initiatives are ongoing: the first distribution agreement with I4T has been formalized, providing for the distribution, through travel agencies, of parametric solutions covering trip cancellation. The offering is also being expanded in the Marine, Cyber and D&O segments through new partnerships and the development of further distribution opportunities;
In terms of product innovation and distribution development, the agreement with UniCredit for the distribution of REVO Cyber Risk has generated premiums of approximately €1.3 million within just a few months of launch. In addition to the continuation of the distribution agreement with Banco Desio, the new Top Up product has been launched in the Credit segment.
KEY IFRS 17 KPIs
A summary table of the Group’s main KPIs as at 30 September 2026, prepared in accordance with IFRS 17, is set out below:
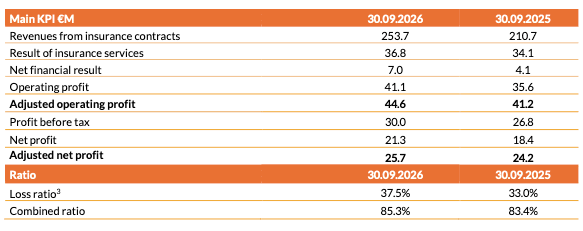
During the period, the following developments are particularly noteworthy:
Against the backdrop of gross written premiums of €314.3 million (+12.0% compared with the third quarter of 2025), insurance revenue amounted to €253.7 million, up 20.4% compared with the same period in 2025;
Gross loss ratio of 37.5%, in line with the trend envisaged in the Business Plan for year-end and including the usual statistical and actuarial adjustments, aimed at taking into account in advance any potential late-reported claims or adverse development of claims already reported. As already highlighted in the half-year results, this ratio was particularly affected by the deterioration in the technical performance of the Agro portfolio, which recorded a loss ratio of 88.2%, compared with 46.6% in the same period of 2025, while remaining significantly better than the market average;
Insurance service result amounted to €36.8 million (€34.1 million as at 30 September 2025), with a further reduction in the cost ratio⁴ (from 18.1% to 17.0%), reflecting the gradual impact of increased operating leverage, in line with the Company’s medium-term target;
The acquisition ratio for the period remained stable compared with the same period in 2025, at 17.8%;
Reinsurance cost ratio stood at 15.9%, improving from 17.5% in the same period of 2025 and from the level recorded during the first six months of the financial year. This trend was driven, during the latest quarter, by an increase in ceded claims and a lower proportion of ceded premiums compared with the third quarter of 2025, partly offset by the lower impact of commissions paid by reinsurers, in line with the gradual reallocation of the portfolio towards non-proportional treaties;
As a result of these developments, the period COR stood at 85.3%, compared with 83.4% in the third quarter of 2025, improving from 86.3% reported at year-end and in line with the target for the first year of the Business Plan;
The investment portfolio made a positive contribution, supported by its limited duration, with an investment result of €7.1 million, compared with €4.9 million in 2025, mainly reflecting higher income, supported by the diversification of the managed portfolio in line with the strategic asset allocation;
Adjusted operating result amounted to €44.6 million, up from €41.2 million in the third quarter of 2025, representing an increase of 8.1% compared with 2025;
Adjusted consolidated net profit amounted to €25.7 million, up from €24.2 million in the third quarter of 2025, with Group shareholders’ equity amounting to €272.6 million (€263.8 million as at 31 December 2025).
SOLVENCY II
The Group’s capital position remains strong, with the Solvency II ratio standing at 214.8% at the end of the third quarter, slightly down from 223.2% recorded as at 31 December 2025.
TREASURY SHARES
As at 30 September 2026, the Company held 229,550 treasury shares, equivalent to approximately 0.784% of its share capital⁵.
FOURTH-QUARTER OUTLOOK
During the final quarter, REVO will continue to implement the projects supporting the execution of the“THE TECHUMAN ERA” Business Plan, through further development of its operating and distribution platform, the strengthening of relationships with the intermediary market through REVO Underwriting, and the development of the Spanish branch.
EVENTS AFTER 30 SEPTEMBER 2026
On 8 October 2026, REVO announced that it would not proceed with the acquisition of Eurocaution S.A., as no agreement had been reached on the Share Purchase Agreement within the expected timeframe.
On 21 October 2026, Simone Lazzaro tendered his resignation, with immediate effect, from his position as Chief Underwriting Officer, due to a conflict of interest arising from his personal entrepreneurial initiatives in the insurance sector.
These events do not affect the Group’s development outlook, and the Group confirms its 2028 targets.
The Manager responsible for preparing the Company’s financial reports, Mr Jacopo Tanaglia, hereby declares, pursuant to Article 154-bis of Legislative Decree No. 58/1998 (the Consolidated Law on Finance), that the accounting information contained in this press release is consistent with the documentary evidence, books and accounting records.
It is noted that the financial and balance sheet information contained in this press release has not been audited.
Notes
¹ IFRS 17 Adjustments = including recurring investment income and expenses and commissions paid by REVO Underwriting to the distribution network, and excluding depreciation and amortisation of tangible and intangible assets, termination indemnity (TFM) payments, non-recurring costs, costs relating to financial debt, VoBA and LTIP.
² Gross IFRS 17 Combined Ratio = (Expenses from insurance contracts issued + reinsurance result) / (Insurance revenue before VoBA).
³ IFRS 17 Loss Ratio = (Gross claims incurred in respect of direct and indirect business) / (Insurance revenue before commissions and VoBA).
⁴ Cost Ratio = (Total operating expenses, net of amortisation of intangible assets, plus other operating expenses/income) / (Insurance revenue before commissions and VoBA).
⁵ Share capital consisting exclusively of ordinary shares